The main intrigue this week centers on the US midterm elections. The first preliminary figures will be available by Wednesday morning, but the final ballot counts can traditionally take weeks
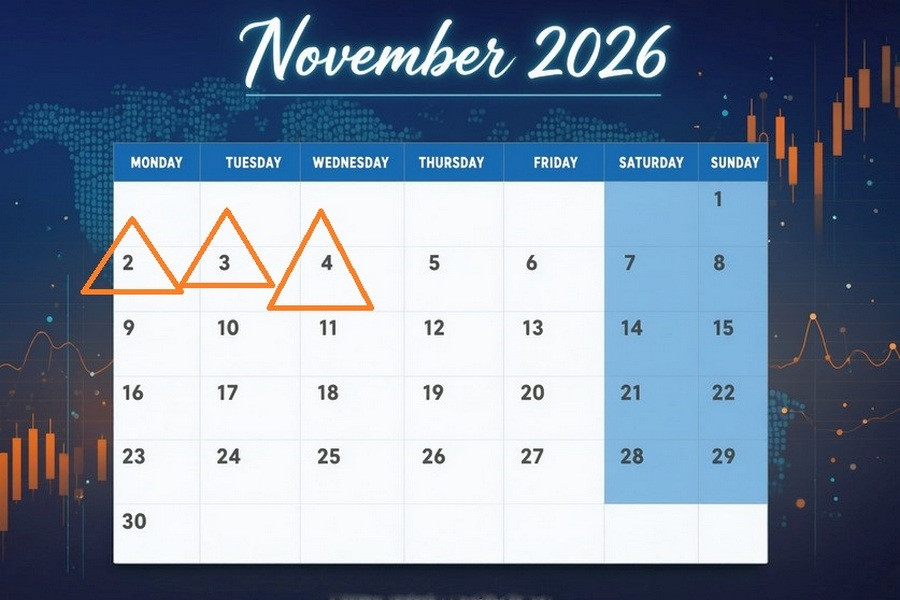
The main intrigue this week centers on the US midterm elections. The first preliminary figures will be available by Wednesday morning, but the final ballot counts can traditionally take weeks. Meanwhile, American voters are setting turnout records — more than 20% of all registered voters have already cast ballots during the four days of early voting. The midterm record from 2022 has officially been broken. According to sources, in 27 states that keep strict party registration data, there is a notable skew:
But it is too early to write off the Republicans. Historically, conservative voters prefer to cast their ballots in person on Election Day itself. On prediction markets such as Polymarket, the odds are hot: the probability of Democrats winning control of the Senate is priced at 69%, while control of the House is almost fully expected to go to the Democratic Party. The dominant backdrop to this vote is deep economic strain on households. Bloomberg reports that today exactly half of the average American family's expenditures go to housing and food alone — the worst cost-of-living record in 15 years. Voters are voting with their wallets.
Why is Wall Street betting on a legislative deadlock?
Let's be blunt: the United States' baseline economic policy is unlikely to change radically after the elections. The Iran conflict, sweeping trade tariffs and the giant federal budget deficit will remain regardless of the Capitol's makeup. But for portfolio investors, the balance of power matters. A divided Congress will inevitably trigger a brutal fight over the federal debt ceiling in 2027. Financial markets must therefore price three key scenarios:
While Washington prepares to count votes, Wall Street's tech sector is playing out its own drama. Big tech stocks have plunged below the levels at which these companies recently raised huge sums to build data centers and buy chips. Investors no longer believe in endless growth on the single word "AI":
In total, offerings exceeding $133 billion are now underwater. Wall Street is flooded with doubts: will these colossal capital expenditures ever pay off? Does this mark the end of blindly funding any project with the "AI" label? As a final worrying note on rising tech risk, the financial world received a cybersecurity alarm: the FBI formally accused a North Korean state-linked hacking group, "TraderTraitor," of an unprecedented attack on a crypto exchange.
As a result, some $6 billion in assets were stolen from Binance. US agencies have unveiled the laundering chain:
The FBI and the IRS issued emergency guidance to private fintech firms, trading venues and validators: addresses associated with TraderTraitor must be immediately and comprehensively blocked. This precedent highlights how vulnerable modern digital infrastructure remains in the face of sophisticated next-generation attacks.
Markets enter November in a crossfire: a voter verdict looms, tech giants' resilience is being reassessed, and geopolitical risks are rising. No respite in sight.
November 2, 01:00 / Australia / S&P Global manufacturing PMI (final, Oct) / prev: 52.0 / actual: 49.6 / consensus: 49.7 / AUD/USD – up
S&P Global's September survey recorded a shift of Australia's manufacturing sector into contraction: the composite PMI fell to 49.6, weighed down by weakening customer demand and the first decline in new orders in three months. Buyers' caution was driven by:
Firms were forced to cut commodity purchases amid ongoing disruptions in maritime logistics. At the same time, rising costs for energy, transport and labour accelerated producer-price inflation, pushing factories to pass on costs in their selling prices. The final October read is expected to show a modest improvement in the activity indicator, which will support the Australian dollar.
November 2, 01:00 / Australia / Melbourne Institute inflation gauge (Oct) / prev: 4.8% / actual: 2.8% / consensus: – / AUD/USD – volatile
The Melbourne Institute's leading inflation gauge recorded a sharp slowdown in price growth to 2.8% from 4.8% a month earlier. The monthly indicator, an early signal for official quarterly statistics, reflected a significant easing of price pressure across key categories of consumer goods and services. In the absence of a consensus forecast, the release could trigger elevated volatility in the Australian dollar.
November 2, 03:30 / Australia / Building approvals (Sep) / prev: 10.9% / actual: 10.3% / consensus: -4.7% / AUD/USD – down
August's building approvals in Australia showed a moderate slowdown in the growth rate to 10.3%, remaining well above the long-run historical norm of 2.5%. Recent strength was supported by completion of previously approved development plans. However, investor interest in new projects continues to be restrained by:
The September release is expected to show a sharp fall in developer activity into deep contraction, which will weigh on the Australian dollar.
November 2, 03:30 / Japan / S&P Global manufacturing PMI (final, Oct) / prev: 54.9 / actual: 54.1 / consensus: 53.3 / USD/JPY – up
Japan's manufacturing sector recorded a slowdown in growth in September: the PMI stood at 54.1, reflecting the most muted rise in output and sales volumes in recent months. Nevertheless, Japanese firms:
This led to near four-year highs in inventories as companies prepared for incoming orders. The final October read is expected to show further cooling of the manufacturing impulse and will weigh on the yen.
November 2, 04:45 / China / RatingDog manufacturing PMI (Oct) / prev: 51.5 / actual: 52.1 / consensus: 52.0 / Brent – down, USD/CNY – up
China's manufacturing PMI from RatingDog rose to 52.1 in September, the fastest expansion since mid-spring, driven by a synchronized pickup in domestic and foreign demand
Factories ramped up production and hiring to meet the order inflow, while a four-month surge in commodity input prices prompted firms to raise selling prices slightly. Business optimism about the outlook improved, though it remained below long-term norms. The October consensus foresees a slight slowdown in the rate of expansion, which will weigh on Brent crude and push USD/CNY higher.
November 2, 08:30 / Australia / RBA commodity-price index (Oct) / prev: 16.2% / actual: 15.5% / consensus: 15.1% / AUD/USD – down
The RBA's September commodity-price index slowed to 15.5%, a six-month low. Downward pressure came from:
These declines outweighed positive moves in agriculture and some non-ferrous metals. In AUD terms, the export commodity basket rose 6.6%, reflecting a moderate exchange-rate effect. Analysts expect further easing in commodity price growth in October, which points to downside risk for the Aussie.
November 2, 10:00 / Germany / Retail sales (Sep) / prev: -2.2% / actual: -0.4% / consensus: -0.3% / EUR/USD – up
Germany's August retail sales fell 0.4%, substantially moderating the pace of decline from July's 2.2% drop. Although consumer spending still lags the long-run average of roughly 0.5%, the slowdown in the contraction of retail turnover indicates households are gradually adapting to current price conditions. The September consensus expects some improvement, which is positive for the euro.
November 2, 11:55 / Germany / S&P Global manufacturing PMI (final, Oct) / prev: 54.3 / actual: 53.9 / consensus: 54.2 / EUR/USD – up Germany's October manufacturing PMI rose to 54.2, marking a two-month high and confirming a sustained improvement in industrial conditions:
Producer-price inflation accelerated to highs not seen since May due to higher oil, commodity and component costs, cooling six-month expectations among manufacturers. Final confirmation of the industrial upturn in Europe's largest economy will support the euro.
November 2, 12:00 / Eurozone / S&P Global manufacturing PMI (final, Oct) / prev: 52.7 / actual: 52.9 / consensus: 52.4 / EUR/USD – down
The eurozone's final manufacturing PMI for October eased to 52.4, a three-month low, reflecting a modest reduction in employment after two months of continuous growth. Amid renewed Middle East tensions, European factories sharply accelerated precautionary purchases of materials, causing near-four-year highs in commodity inventories and the largest lengthening of lead times since the start of summer. Surging costs for energy, fuel and transport triggered a sharp rise in input-cost inflation, exceeding annual averages. The next release is expected to show a slowdown in the bloc's industrial expansion, which will put pressure on the euro.
November 2, 12:30 / UK / S&P Global manufacturing PMI (final, Oct) / prev: 51.9 / actual: 51.7 / consensus: 52.8 / GBP/USD – up
UK manufacturing showed the most significant improvement in business conditions since late spring in October. The composite PMI strengthened to 52.8 thanks to:
Despite locally restrained hiring, shortages of electronic components and maritime logistics disruptions caused by the Middle East crisis — which have depleted inventories for a fifth consecutive month — British manufacturers' optimism has firmed on the back of prospects for large defence and AI-related infrastructure investments. Expected acceleration in manufacturing activity will support the pound.
November 2, 16:30 / Canada / S&P Global manufacturing PMI (final, Oct) / prev: 53.5 / actual: 53.0 / consensus: 51.5 / USD/CAD – up
Canada's manufacturing PMI slipped to 51.5 in September, the weakest reading in six months. Headwinds included:
Rising energy prices and material shortages pushed producer-cost inflation to its highest since mid-2022, forcing firms to draw down inventories and weighing on business confidence. Slower industrial expansion will pressure the Canadian dollar.
November 2, 16:45 / US / S&P Global manufacturing PMI (final, Oct) / prev: 53.9 / actual: 55.9 / consensus: 56.0 / USDX (6?currency USD index) – up
The final S&P Global manufacturing PMI for the US in October registered 56.0, marking the most confident improvement in manufacturing conditions since May 2022. Although output growth and order levels showed some moderation, the indicators retain a substantial buffer. Factory hiring accelerated to the strongest pace since spring 2012. Firms continued to rebuild commodity inventories amid the largest lengthening of supplier lead times in two years. Confirmation of robust industrial dynamics and firm labour demand will support the US dollar.
November 2, 17:00 / US / ISM manufacturing PMI (Oct) / prev: 54.6 / actual: 54.5 / consensus: 54.6 / USDX – up
The ISM survey for September confirmed continued expansion in US manufacturing: the PMI held at 54.5, supported by a synchronized pickup in new orders and hiring. The main strain for firms remained a sharp surge in the commodity prices index to nearly 78, reflecting higher metals, fuel and import tariffs; together with supply delays from the Middle East, this has increased caution among managers. The October report consensus expects manufacturing momentum to strengthen, which will support the dollar.
November 2, 17:00 / US / ISM manufacturing employment (Oct) / prev: 51.2 / actual: 52.7 / consensus: 53.0 / USDX – up The ISM employment subindex for manufacturing rose to 52.7 in September, signaling a return of labour demand. The pickup in hiring was led by:
Analysts expect further acceleration in manufacturing employment in October, which will boost the dollar.
November 3, 06:30 / 07:30 / Australia / RBA rate decision & press conference / prev: 4.35% / actual: 4.60% / consensus: 4.85% / AUD/USD – up
The Reserve Bank of Australia unanimously raised the cash rate by 25 bps to 4.60%, the highest borrowing cost since 2011 and the fourth tightening round this year. The decision was justified by:
The Reserve Bank of Australia unanimously raised the cash rate by 25 bps to 4.60%, the highest borrowing cost since 2011 and the fourth tightening round this year. The decision was justified by:
Despite cooling consumer spending, falling housing prices in major cities and tighter mortgage lending, high capacity utilisation and businesses' willingness to pass higher costs through to prices kept the board firmly hawkish. Expectations of further tightening will support the Australian dollar.
November 3, 18:00 / US / JOLTs job openings (Sep) / prev: 7.335m / actual: 7.079m / consensus: 7.130m / USDX – up
The JOLTs report showed job openings fell by 256k in August to a five-month low of 7.079m. Cooling labour demand was notable in:
At the same time, hirings (5.2m) and total separations (5.1m) remained balanced, indicating no large-scale layoffs. Renewed corporate hiring will support the dollar.
November 3, 18:00 / US / JOLTs quits (Sep) / prev: 3.089m / actual: 3.066m / consensus: 3.050m / USDX – down
Quits fell to 3.07m in August, keeping the quits rate at 1.9% — near lows not seen since 2020. Declines in wholesale trade and education offset a local rise in durable-goods sectors, reflecting households' caution amid:
Reduced labour mobility signals lower worker confidence, which will weigh on the dollar.
November 3, 18:00 / US / Factory orders (Sep m/m) / prev: 0.8% / actual: 0.1% / consensus: 1.2% / USDX – up
New orders to US manufacturers rose a modest 0.1% in August, slowing sharply after July's gain. Small increases in orders for electrical equipment, primary metals and machinery supported the nondurable goods segment (+0.3%). A pickup in new industrial contracts will support the greenback.
November 3, 18:00 / US / RCM/TIPP economic optimism index (Nov, leading) / prev: 45.6 / actual: 46.8 / consensus: 46.2 / USDX – down
The RealClearMarkets/TIPP consumer-sentiment barometer rose to 46.8 in October, the highest since spring, despite turbulence in the Treasury market. All subindices improved:
Stronger consumer confidence will weigh on the dollar.
November 4, 00:30 / US / API crude inventories (weekly) / prev: -4.93m / actual: -2.031m / Brent – volatile
API reported a draw of more than 2m barrels of commercial crude for the week to Oct. 23, defying expectations of a build. Additional tightening came from draws at Cushing (-453k bbl) and a drop in U.S. daily production to 13.269m b/d, partly offset by increases in motor-fuel stocks:
Lack of an official consensus and divergent flows between crude and product markets may raise Brent volatility.
November 4, 03:30 / Australia / Business activity index (Oct) / prev: -1.6 / actual: -24.2 / consensus: -24.9 / AUD/USD – down
September survey showed a sharp collapse in Australian business sentiment to -24.2 due to mounting uncertainty, credit constraints and a second wave of fuel and refinery price rises.
A critical gap between input costs and selling prices (43.2) squeezed margins and dropped capacity utilisation to 77.2%. Continued corporate stress will pressure the AUD.
November 4, 01:00 / Australia / S&P Global services PMI (final, Oct) / prev: 53.2 / actual: 51.2 / consensus: 47.8 / AUD/USD – down
Australia's services sector slid into contraction in October for the first time since May. The composite PMI fell to 47.8 amid a sharp slowdown in new client inflows. Weak demand was driven by:
Firms passed higher costs to consumers despite hiring to clear backlogs. Confirmation of a services slowdown will weigh on the AUD.
November 4, 04:45 / China / RatingDog services PMI (final, Oct) / prev: 51.4 / actual: 51.6 / consensus: 51.5 / Brent – down, USD/CNY – up
China's services PMI rose to 51.6 in September, the highest since early summer, supported by:
Service firms increased employment for the fifth consecutive month but rising labour, input and energy costs pushed service-sector input-cost inflation to a 4.5-year high. Any softening in China's services momentum will pressure Brent and push USD/CNY higher.
November 4, 11:55 / Germany / S&P Global services PMI (final, Oct) / prev: 49.7 / actual: 52.9 / consensus: 51.7 / EUR/USD – down
Germany's services PMI held at 52.9 in September, confirming a return to expansion. New orders stalled as clients delayed budget approvals, leading to renewed declines in unfinished work. Job creation continued for a third month, but hiring remained muted, and input-cost inflation eased thanks to lower motor-fuel prices. A slowdown in services will pressure the euro.
November 4, 12:00 / Eurozone / S&P Global services PMI (final, Oct) / prev: 51.6 / actual: 53.0 / consensus: 51.7 / EUR/USD – down
Eurozone services activity peaked at 53.0 in September before facing slowing momentum. With France's services slipping toward contraction and weaker new-order inflows elsewhere, job creation fell to a five-month low. Lower input-cost inflation accompanied easing pressure on manufacturing capacity, but business expectations weakened. A slowdown in services will weigh on the euro.
November 4, 12:30 / UK / S&P Global services PMI (final, Oct) / prev: 52.5 / actual: 52.1 / consensus: 53.1 / GBP/USD – up The UK services survey recorded continued expansion in October, boosted by:
New orders growth supported renewed hiring despite management caution and high costs. A pick-up in services activity will support the pound.
November 4, 13:00 / Eurozone / CPI preliminary (Oct) / prev: 3.2% / actual: 3.8% / consensus: 3.9% / EUR/USD – up
Eurozone annual CPI jumped to 3.8% in September, the highest since autumn 2023. Key drivers were a large rise in energy tariffs (+18.9%), higher services (+3.2%) and food (+1.3%), pushing core inflation to 2.5%. Price pressure spread across major economies, lifting rates in Germany, France, the Netherlands, Italy (to 4.2%) and Spain (to 5.0%). Continued high inflation will increase ECB tightening pressure and support the euro.
November 4, 16:15 / US / ADP employment change (Oct) / prev: 36k / actual: 90k / consensus: 65k / USDX – down
ADP's private sector employment estimate rose to 90k in September, reversing three months of slowdown. Job gains were concentrated in:
This offset declines in finance and professional services. Stable payroll gains alongside steady wages show no sharp corporate labour-market deterioration. Slower private-sector hiring would weigh on the dollar.
November 4, 16:30 / Canada / trade balance (Sep) / prev: 0.79bn CAD / actual: 4.20bn CAD / consensus: 3.70bn CAD / USD/CAD – up
Canada's trade surplus jumped to CAD 4.2bn in August, the highest since spring 2022, despite a stronger loonie. Exports rose 2.5% as commodity shipments gained (+4.7%) amid:
Imports fell 2.0% due to a drop in motor-vehicle imports (-8.8%) and a sharp slump in unprocessed precious-metal and platinum-group shipments (-40.0%). A narrowing trade deficit will support the loonie.
November 4, 16:30 / US / trade balance (Sep) / prev: -92.8bn / actual: -105.6bn / consensus: -108.8bn / USDX – down
The US trade deficit widened to $105.6bn in August, the largest gap since spring 2025, driven by record imports of $420.8bn as purchases of:
Exports rose to $315.2bn, partially offsetting the widening gap. The larger trade shortfall will weigh on the dollar.
November 4, 17:00 / Canada / S&P Global composite PMI (final, Oct) / prev: 47.8 / actual: 48.7 / consensus: 48.5 / USD/CAD – up
Canada's composite PMI held at 48.7 in September, remaining below neutral for the fourth consecutive month. Services contraction continued while factory output showed modest growth. New orders and employment fell in tandem. Rising producer costs, but easing selling-price growth and a five-month high in business optimism set the stage for gradual stabilisation. Continued macro weakness will pressure the loonie.
November 4, 17:45 / US / S&P Global services PMI (final, Oct) / prev: 56.5 / actual: 58.8 / consensus: 57.9 / USDX – down
US services PMI stood at 57.9 in October, extending a seven-month expansion streak and holding near multi-year highs. Domestic demand drove the strongest inflow of new orders in 2.5 years, while foreign contracts saw the biggest increase since mid-2023. Rising operating costs for fuel, staff, utilities and insurance pushed input cost inflation to summer-2022 highs, cooling six-month output expectations. A slowdown in services growth vs. September will pressure the dollar.
November 4, 18:00 / US / ISM services PMI (final, Oct) / prev: 55.4 / actual: 54.9 / consensus: 56.0 / USDX – up
The ISM services survey confirmed the sector remained in expansion for the 27th consecutive month in September, despite the index easing to 54.9.
Key challenges remain high input-cost inflation (price subindex reached 74), trade tariffs and weak external demand. Stronger services dynamics will support the dollar.
November 4, 18:00 / US / ISM services business activity (Oct) / prev: 61.7 / actual: 56.5 / consensus: 56.0 / USDX – down
The ISM business-activity subindex for services eased to 56.5 in September after August's surge to multi-year highs. Despite the cooling, the index remains near its long-run average of 57.25, retaining a sizeable buffer. A softer business impulse will weigh on the greenback.
November 4, 18:30 / US / EIA crude inventories (weekly) / prev: -3.061m / actual: -1.892m / consensus: -2.481m / Brent – up
The DoE weekly report showed a fourth consecutive draw in commercial crude stocks (-1.892m bbl to Oct. 23), confirming tight physical supply. Draws at Cushing (-624k bbl) and a near-1.5m bbl fall in distillate stocks were accompanied by a 796k b/d drop in net imports and slightly lower refinery runs, outweighing gasoline builds. Reduced hydrocarbon supplies will support Brent.
Nov 2, 12:45 / Eurozone / Speech by Boris Vujcic (ECB Governing Council) / EUR/USD
Nov 2, 15:00 / Eurozone / Speech by Joachim Nagel (ECB Governing Council) / EUR/USD
Nov 2, 19:15 / US / Speech by Austan Goolsbee (President, Federal Reserve Bank of Chicago) / USDX
Nov 3, 07:30 / Australia / Speech by RBA Governor Michele Bullock / AUD/USD
Nov 3, 11:45 / Eurozone / Speech by Pedro Machado (ECB Supervisory Board) / EUR/USD
Nov 3, 17:00 / Eurozone / Speech by Sharon Donnery (ECB Supervisory Board) / EUR/USD
Nov 3, 19:00 / Canada / Speech by Bank of Canada Governor Tiff Macklem / USD/CAD
Nov 3, 21:00 / Eurozone / Speech by Joachim Nagel (ECB Governing Council) / EUR/USD
Nov 3, 21:15 / Eurozone / Speech by Olaf Sleijpen (ECB Supervisory Board, DNB Governor) / EUR/USD
Nov 4, 16:20 / Eurozone / Speech by Philip Lane (ECB Supervisory Board) / EUR/USD
Also expect speeches from major central bank officials these days. Their comments typically spark FX volatility as they can signal future policy paths.

SZYBKIE LINKI
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 Skontaktuj się z ForexMart